Published September 29, 2026
A VA Appraisal Is Not Your Home Inspection: What Military Buyers Should Schedule
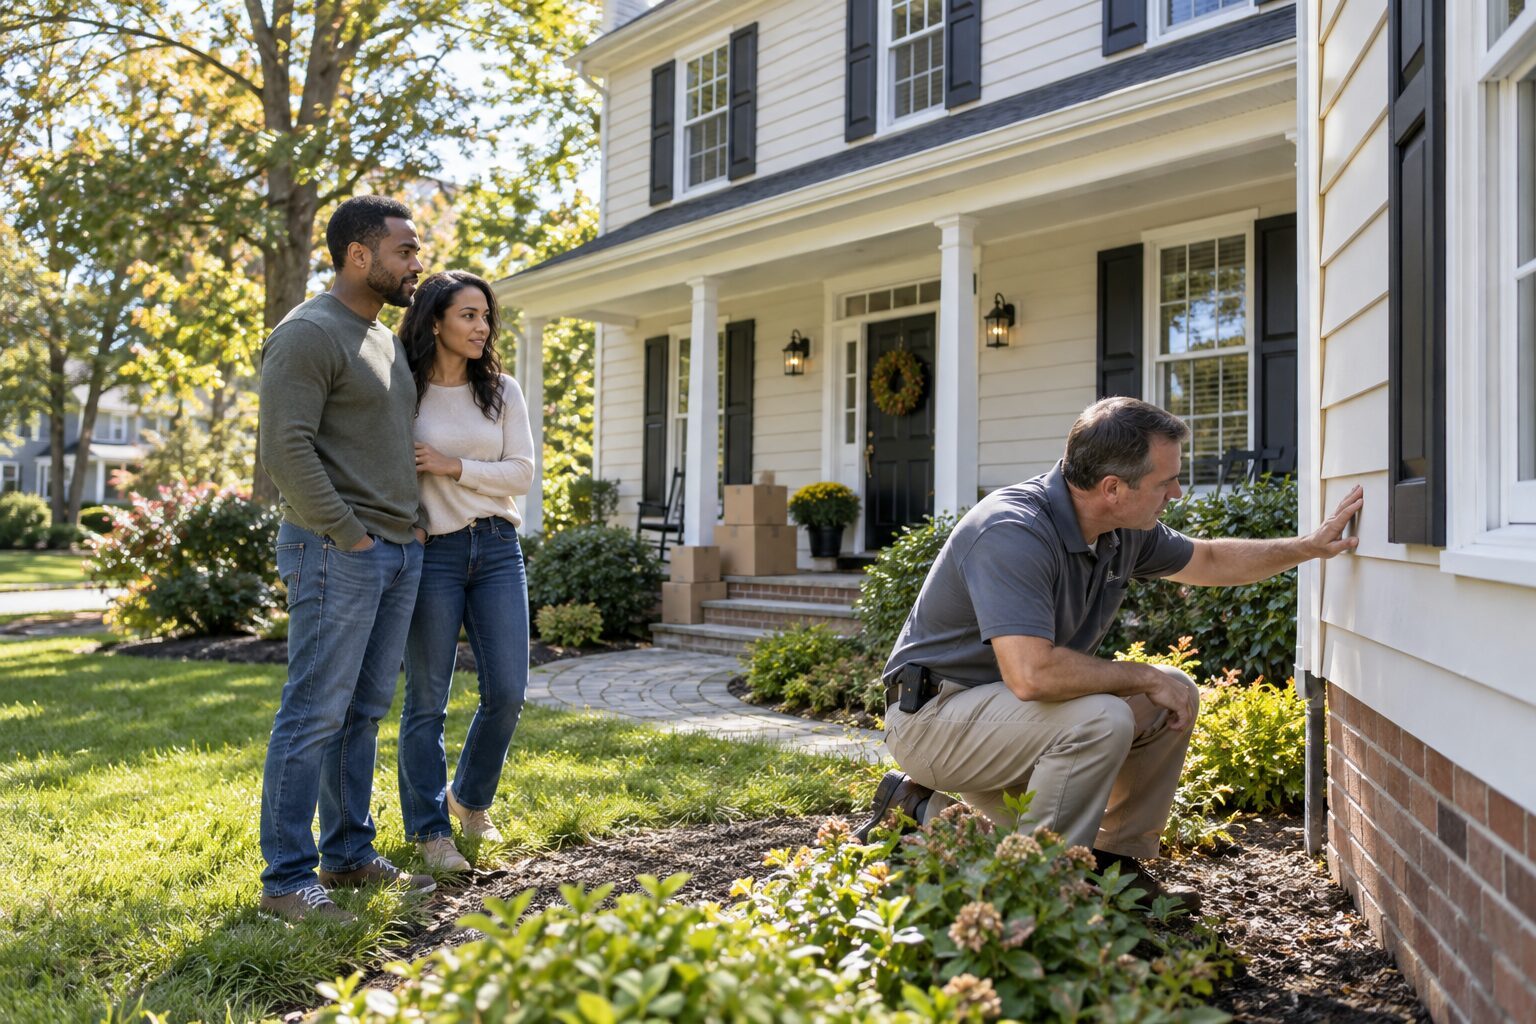
Southern Maryland VA purchases frequently involve older homes, wells, septic systems, crawlspaces, waterfront exposure and long commutes to Joint Base Andrews, NAS Patuxent River or Washington-area duty stations. A general inspection may lead to specialty reviews while the VA appraisal separately identifies value or minimum-home or parcel concerns.
Start With the Choice the Client Must Make
A VA appraisal supports the lender’s collateral decision and addresses VA minimum home or parcel requirements, but it is not a substitute for a purchaser-selected home inspection. Military purchasers need both processes organized correctly because they answer different questions and create different contract decisions. For The Riley Team, the client’s decision sets the research order. We identify the controlling source, then establish when that answer is needed.
Assemble the Evidence Before Discussing Terms
- VA financing addendum and complete ratified contract
- Lender’s appraisal order confirmation and Notice of Value when issued
- Independent home inspection report and specialist reports
- Seller disclosure or disclaimer and available repair records
- Well, septic, water-quality, pest and permit documentation when applicable
- Written repair agreement, invoices, permits and completion evidence
One organized file gives everyone the same factual starting point. An item remains unresolved until the responsible source provides it.
Practical Clues Worth Investigating
- A purchaser is told the VA appraiser will perform a full home inspection
- Inspection timing is delayed while everyone waits for the appraisal
- Peeling paint, unsafe access, active moisture or broken systems are visible
- The contract price exceeds the VA value and no response plan is calendared
- Repairs are promised without identifying who completes and verifies them
- The purchaser waives inspections because the loan is guaranteed by VA
Purchaser’s Action Plan
- Keep inspection and appraisal decisions on separate calendar tracks.
- Hire a qualified inspector and relevant specialists within the contract period.
- Ask the lender which observed conditions may affect VA loan approval.
- Review the Notice of Value and any required repairs promptly.
- Price repair, appraisal-gap and termination choices before response deadlines.
- Complete a careful final walkthrough and retain all completion evidence.
Owner’s Preparation Plan
- Prepare safe access to attics, crawlspaces, utilities and outbuildings.
- Address obvious safety and deferred-maintenance concerns before appraisal.
- Gather permits, invoices and system records that may answer questions quickly.
- Evaluate repair requests separately from VA-required appraisal conditions.
- Use licensed contractors when the scope or lender requires qualified work.
- Do not advertise a home as VA approved based on a prior transaction.
The Riley Team’s Contract Approach
Dawn labels each issue by source: purchaser inspection, specialist report, VA appraisal, lender underwriting or insurance. She avoids using one professional’s conclusion as a substitute for another. The repair request identifies the condition, proposed remedy, documentation and deadline while the VA value response follows the financing addendum and lender instructions.
A Lusby VA purchaser receives a satisfactory value, but the independent inspector finds a failing deck connection and evidence of crawlspace moisture. The appraisal result does not erase those concerns. Dawn obtains specialist scopes within the inspection period, separates the safety repair from optional improvements and coordinates any lender-required documentation before the parties commit to a remedy.
Questions Southern Maryland Clients Ask
Is a VA appraisal a home inspection?
No. The appraisal addresses value and VA minimum home or parcel requirements for the loan. A home inspection is a purchaser-selected evaluation of the home or parcel’s systems and condition.
When does VA require purchasers to get a home inspection?
VA strongly encourages purchasers to obtain an independent inspection, but a purchaser should verify current loan and contract requirements with the lender and agent.
What are VA minimum home or parcel requirements?
They are VA standards addressing whether the home or parcel is safe, sanitary and structurally sound for loan-guaranty purposes. The appraiser and lender apply the current VA guidance to the specific home or parcel.
Under what circumstances may a home appraise at value and still have serious defects?
Yes. Value and condition evaluate are not the same as a comprehensive inspection. A purchaser should evaluate defects through qualified inspectors and specialists.
Who chooses the home inspector?
A purchaser should select the inspector, understand the scope and decide which specialty inspections are needed. The appraiser is assigned through the lender’s VA process.
What happens if the VA value is below the contract price?
The financing addendum and current VA process control the purchaser’s options and timing. The parties may negotiate, the purchaser may provide additional funds if permitted, or the contract may end under applicable protection.
Must every inspection item be repaired for VA financing?
No. Inspection findings and VA-required conditions are different lists. The lender decides what must be satisfied for the loan, while the parties negotiate inspection issues under the contract.
Under what circumstances may the owner complete VA repairs after settlement?
Only if the lender and applicable program permit a specific escrow or completion arrangement. Do not assume a repair may be postponed without written lender approval.
When does a prior VA appraisal transfer to a new purchaser?
Do not rely on a prior transaction. The current purchaser’s lender and VA process determine the appraisal and documentation required for the new loan.
How should military orders affect inspection planning?
PCS deadlines make early scheduling especially significant. Purchasers should leave time for specialists, repair verification, lender evaluate, household-goods coordination and a final walkthrough.
Related RileyTeam.net Real Estate Guides
- Which Maryland Contract Dates Need Immediate Calendar Reminders?
- Before the Pool Becomes the Selling Point, Verify the Equipment and Safety
- What Does a Home Warranty Actually Cover After Settlement?
- Is the Deed Still Correct? A Maryland Property-Record Safety Check
- Moving Out of Maryland? Check Seller Withholding Before You List
- Will Your Home Sale Be Taxable? Build the Basis File Before Closing
- Can You Sell a Maryland Rental While the Tenant Still Lives There?
- A Neutral Real Estate Plan for Selling the House During Divorce
- How Does a Reverse Mortgage Get Paid Off When the Home Sells?
For more about Dawn Riley’s experience and negotiation background, visit DawnRiley.net.
Sources Cited
- U.S. Department of Veterans Affairs, VA Home Buyer’s Guide
- VA, home buying process
- VA Lenders Handbook
- Maryland REALTORS, VA Financing and inspection forms
General real estate information only. Consult the appropriate legal, lending, tax, insurance, engineering or other licensed professional for the home or parcel.